The quick answer
A masonry house has exterior walls built of brick, block or stone that carry the load. A frame house has walls built on a wood or light-metal frame. Brick on the outside doesn't settle it: brick veneer over a wood frame is usually rated as frame. To find out what you have, check your policy declarations page, then confirm with the wall itself or an inspector.
Your insurer puts your house into a construction class when it prices the policy. If the class is wrong, you could pay a frame rate on a masonry house, or hold a policy that describes your home inaccurately. This guide covers the standard classes, what "masonry" means for a house, and how to check yours.
Rules differ by insurer and state. The sources we read are rating guides and consumer pages, not a single legal standard, so treat the details below as the common pattern and confirm with your own carrier.
The six standard construction classes
Many insurers use the six classes from ISO, the company that writes standard insurance forms. Most houses fall into the first two. The descriptions below are plain-English summaries of how insurance training sources describe them.
| Class | Name | In plain English |
|---|---|---|
| 1 | Frame | Walls, floors and roof are wood or light-gauge metal. Brick or stone veneer can sit on the outside. |
| 2 | Joisted masonry | Exterior walls are brick, concrete block or similar masonry. Floors and roof are wood or light metal. |
| 3 | Noncombustible | Steel framing with metal siding or similar panels and a metal roof. |
| 4 | Masonry noncombustible | Masonry or fire-resistive walls, with unprotected noncombustible floors and roof such as metal decking. |
| 5 | Modified fire resistive | Noncombustible floors, roof and supports with a fire rating of at least one hour. |
| 6 | Fire resistive | Reinforced concrete floors, roof and supports with a fire rating of at least two hours. |
Classes 3 to 6 are mostly commercial and large-building categories. A typical house is class 1 or class 2. Training sources word the middle classes a little differently, so don't read the table as exact policy language.
Masonry versus brick veneer
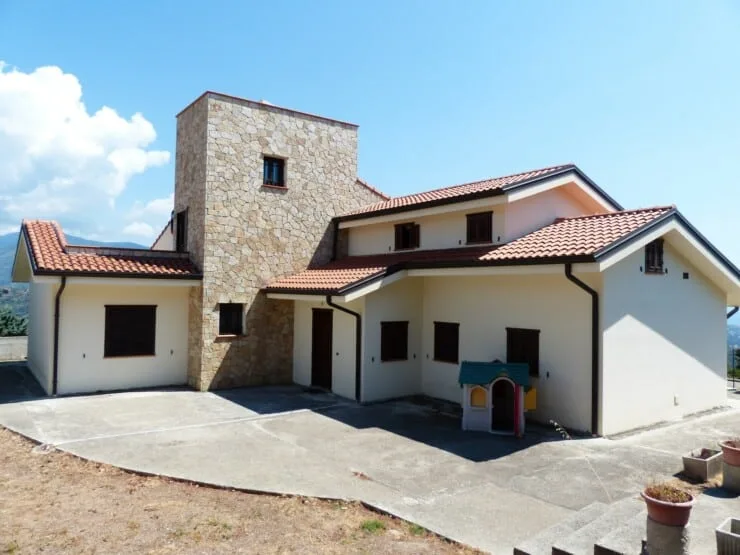
This is where most confusion starts. A true masonry wall is made of brick, block or stone and holds the house up. Brick veneer is a single layer of brick tied to a wood-frame wall. The brick is decoration and weather protection. The frame does the structural work.
Insurance sources generally put brick veneer over wood in the frame class. One insurer's Alabama guide goes further and sets rules for mixed walls: the dominant material (51 percent) decides whether the house rates as frame or as brick veneer, and stucco counts as frame over wood but as brick veneer over masonry. It also treats vinyl siding as frame. Some states and insurers use a separate "masonry veneer" category with its own rate, so your veneer house may not fall at either end.
Does it change the premium?
Often, but not always, and not by a fixed amount. The Wisconsin insurance commissioner's office says construction type is one factor in cost, that brick is more fire-resistant than wood framing, and that insuring a wood-framed home sometimes costs more. The word "sometimes" matters.
One consumer-research article (Checkbook) puts numbers on it: frame costing about 8 percent more than masonry where fire protection is good, and about 20 percent more where it is poor. We couldn't confirm the date or region of those figures, so read them as an example of direction, not a quote for your home. Fire protection class, roof, age, location and coverage amount all move the price too.
We found nothing that supports a flat rule that masonry is cheaper. Our judgement: the class is one input among many, so a masonry house in a poorly protected area can still cost more than a frame house near a fire station.
How to find out what your house is
- Policy declarations page. Look for "construction," "construction type" or "exterior walls." It shows what your insurer has on file.
- Purchase paperwork. The inspection report, appraisal and listing often state the wall system.
- County assessor record. Many assessor sites list exterior wall type. It is often entered from old data, so check it against the house.
- Building plans or permits. The original plans show the wall section, which settles it.
- Look at the walls. Hunker's guide lists clues for solid brick: header rows where bricks are turned end-on (often about every sixth row), heavy stone or concrete lintels or arches over openings, and windows set about a brick's length back from the outer face. Weep holes (finger-sized drainage gaps) point to veneer.
- Ask a pro. A home inspector or your insurer's inspector can confirm the wall type, often from an attic, basement or door opening.
None of the visual clues is final alone. The guide itself says age and pattern vary, and a brick exterior can be added to a house at any time. Weigh several clues together. If the front is brick but the sides and back are siding, the brick is likely veneer.
If your insurer has it wrong
- Ask your agent or insurer what construction class is on your policy and how they got it.
- Send proof: plans, the inspection report, photos of the wall section at an opening, or a written statement from a licensed inspector.
- Ask them in writing to re-rate the policy, and ask whether any premium difference is refunded.
- If they refuse, try a formal appeal with the company. After that, you can file a complaint with your state department of insurance. The NAIC advises trying the insurer first, then keeping your policy number, documents and a dated log of contacts.
Correcting the record also protects you at claim time. A policy that describes your house wrongly gives the insurer something to argue about. Ask your agent how your state handles that.
Frequently Asked Questions
Is brick veneer masonry for insurance?
Usually not. Insurance sources generally classify brick veneer over a wood frame as frame, though some states and insurers use a separate masonry veneer category. Ask your insurer which one applies.
Are masonry homes always cheaper to insure?
No. Sources say frame homes sometimes cost more because brick resists fire better than wood framing. Fire protection, location, roof, age and coverage amount also affect price.
Where do I find my home's construction type?
Start with the declarations page of your policy. Then check your inspection report, the county assessor record and any building plans.
Can I tell solid brick from veneer by looking?
Sometimes. Header rows, heavy lintels and deep window set-back suggest solid brick. Weep holes suggest veneer. No single sign is final, so get an inspector to confirm.
Sources
- Troxell Insurance: ISO classes (the six construction classes)
- Homeowners of America: Construction definitions, Alabama (frame, brick veneer, 51 percent mixed-wall rule)
- Wisconsin Office of the Commissioner of Insurance: Homeowner's insurance FAQ (construction type and cost)
- Checkbook: How are homeowners insurance rates determined (frame versus masonry premium example)
- Hunker: How to tell if a house has brick veneer vs. solid brick walls (visual clues)
- NAIC: How to file a complaint (complaint steps)
The county assessor and building plans steps are our own suggestions. Rules vary by state and insurer, so confirm with your carrier.